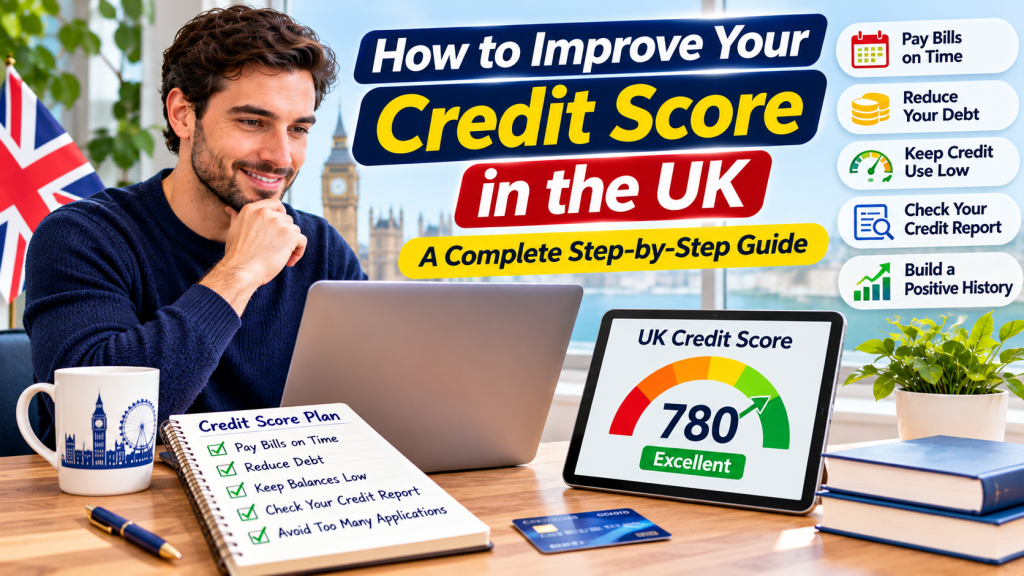

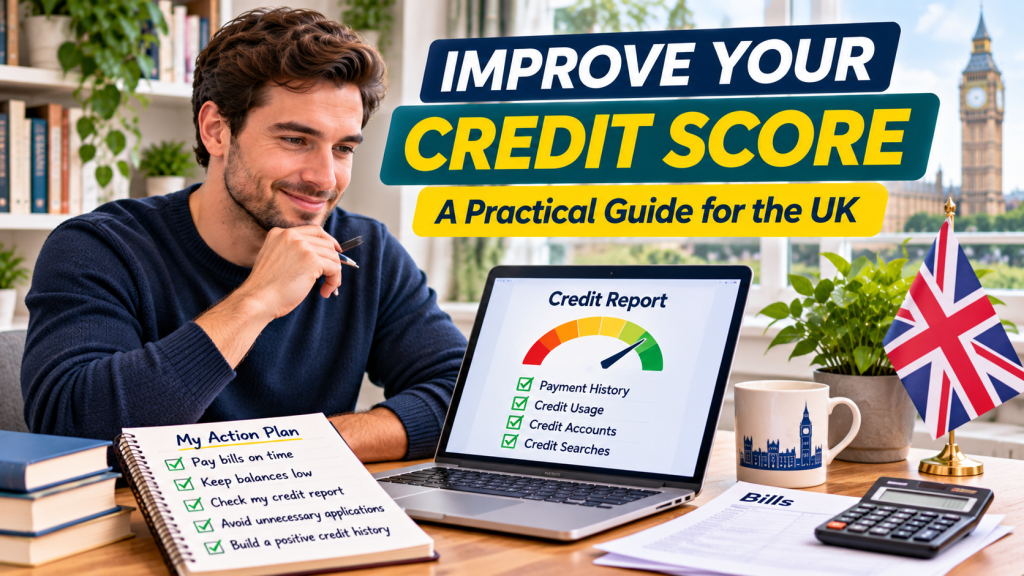
Your credit score can play an important role in your financial life in the United Kingdom. Whether you want to apply for a credit card, personal loan, mobile phone contract or mortgage, your credit history may influence how a lender assesses your application.
If your credit score is low, you may find it harder to access certain financial products or qualify for competitive interest rates. The good news is that there are practical steps you can take to improve your credit profile over time.
In the UK, credit reference agencies collect information about your borrowing and repayment history. They use this information to create credit reports and calculate credit scores.
This guide explains how to improve your credit score in the UK, check your credit report for free, correct mistakes, manage existing debt and build a stronger credit history.
1. Understand How Credit Scores Work in the UK
A credit score is a number used to summarise information in your credit history. It can help indicate how you have managed borrowing in the past.
In the UK, credit reference agencies (CRAs) collect financial information and create credit reports.
The three main credit reference agencies are:
- Experian
- Equifax
- TransUnion
Crediva also provides credit reference services in the UK.
Each agency may hold slightly different information and use its own scoring system. This means your credit score may not be the same across all agencies.
For example, one agency might show a score of 650, while another may use a different numerical range and display a different number.
Important: Lenders do not all use the same credit score. They may use their own internal scoring systems and consider other information, including affordability and your existing financial commitments.
Therefore, having a high score does not guarantee that your application will be approved.
2. Check Your Credit Report Regularly
Before trying to improve your credit score, understand what is currently recorded on your credit report.
Your credit report may contain:
- Personal details and current address
- Previous addresses
- Credit card accounts
- Personal loans
- Mortgage information
- Overdrafts
- Payment history
- Missed or late payments
- Defaults
- County Court Judgments (CCJs), or Decrees in Scotland
- Financial associations with other people
- Electoral register information
Checking your credit report can help you identify problems that may affect your applications.
You can request a free statutory credit report from each main credit reference agency. Checking your own report does not harm your credit score.
Try to check all three main agencies because their records may not be identical.
3. Register on the Electoral Roll
Registering to vote at your current address can help credit reference agencies verify your identity and address.
Lenders may use electoral register information as part of their checks when assessing applications.
If you are eligible to register to vote in the UK, make sure your details are correct and updated whenever you move home.
You can register through the official GOV.UK website.
If you are not eligible to vote in the UK, you can still build a credit history. Keep proof of your address, such as bank statements or utility bills, and check with the credit reference agencies about adding a Notice of Correction if appropriate.
4. Always Pay Your Bills on Time
Payment history is an important part of your credit profile.
Late or missed payments on credit accounts can negatively affect how lenders view your borrowing history.
Make sure you pay your required payments on time, including:
- Credit card bills
- Personal loan instalments
- Mortgage payments
- Car finance payments
- Mobile phone contracts where credit information is reported
- Other credit agreements
One practical solution is to set up Direct Debits for regular payments.
You can also set calendar reminders a few days before each payment date.
If you are struggling to make a payment, contact the lender before missing it. They may be able to discuss alternative arrangements.
5. Keep Your Credit Card Balances Under Control
Your credit utilisation is the amount of available credit you are using.
For example, suppose your credit card limit is £2,000 and your outstanding balance is £1,000.
Your credit utilisation is:
£1,000 ÷ £2,000 × 100 = 50%
Using a large proportion of your available credit may be viewed negatively by some lenders and scoring models.
Consider these steps:
- Avoid regularly using your entire credit limit.
- Pay down outstanding balances where possible.
- Avoid unnecessary credit card spending.
- Pay more than the minimum amount when affordable.
- Keep track of your statement balance and payment date.
There is no single utilisation percentage that guarantees a good credit score. Lower balances may help, but lenders assess your overall circumstances.
6. Avoid Making Too Many Credit Applications
Every time you apply for certain financial products, a lender may carry out a hard credit search.
Hard searches can be visible to other lenders and may affect your credit score.
Making several applications within a short period can make it appear that you are relying heavily on credit.
Before applying for a new credit card or loan:
- Check the eligibility requirements.
- Use an eligibility checker where available.
- Compare interest rates and fees.
- Avoid applying for several products at the same time.
- Apply only when you have a genuine need.
Many eligibility checkers use soft searches, which do not affect your credit score.
7. Correct Errors on Your Credit Report
Incorrect information can make your credit history look worse than it really is.
For example:
- An account that does not belong to you
- A payment incorrectly marked as missed
- An outdated address
- A debt that has already been settled
- Incorrect personal details
- An unfamiliar credit application
If you find an error, contact the credit reference agency and the organisation that supplied the information.
Explain the problem and provide supporting evidence where possible.
The agency can investigate the issue with the information provider and update the report if an error is confirmed.
If you cannot resolve the issue, you can consider making a complaint to the Information Commissioner’s Office (ICO), depending on the circumstances.
Never pay a company that promises to remove accurate negative information from your credit report.
8. Build a Credit History if You Have Never Borrowed
Having little or no credit history can make it difficult for lenders to assess how you manage borrowing.
If you have never used credit, you may have a limited credit file.
You can gradually build a credit history by:
- Opening and managing a suitable bank account.
- Paying eligible credit agreements on time.
- Using a credit card responsibly if you genuinely need one.
- Keeping your personal and address information accurate.
- Avoiding unnecessary borrowing.
You do not need to take out a loan just to create a credit history.
If you choose a credit card, compare its interest rate, fees and eligibility requirements. Only borrow what you can afford to repay.
9. Keep Old Credit Accounts in Good Standing
The length and stability of your credit history may be relevant to some credit scoring systems.
Keeping a well-managed account open may help maintain a longer record of responsible credit use.
However, you should not keep an expensive or unnecessary account just to protect your credit score.
Before closing an account, consider:
- Whether it has an annual fee
- Whether you use it regularly
- Whether closing it will affect your available credit
- Whether there are outstanding balances
- Whether the account is linked to any other financial agreement
The right decision depends on your personal circumstances.
10. Check for Financial Associations
Your credit report may include information about people with whom you have a financial connection.
For example, you may become financially associated with someone through:
- A joint mortgage
- A joint loan
- A joint credit account
Simply living with someone, sharing an address or being married does not automatically create a financial association.
If you have closed a joint financial account and no longer have a financial connection, you can ask the relevant credit reference agencies whether a Notice of Disassociation is appropriate.
This can help ensure that your report does not continue to show an outdated financial link.
11. Manage Existing Debt Carefully
High levels of debt and missed payments can make it harder to obtain new credit.
If you have multiple debts, prepare a clear repayment plan.
List:
- The name of each lender
- The outstanding balance
- The interest rate
- The minimum payment
- The payment due date
You can then decide how to repay your debts.
Debt Avalanche Method
Pay the minimum required amount on all debts and direct extra money towards the debt with the highest interest rate.
This can reduce the total interest paid when other factors are equal.
Debt Snowball Method
Pay the minimum required amount on all debts and direct extra money towards the smallest balance first.
Clearing smaller debts can help some people stay motivated.
If you cannot afford essential bills or debt repayments, seek free debt advice rather than taking out more expensive borrowing.
12. Add Rental Payments to Your Credit History
If you rent a property in the UK, you may be able to have your rental payment information added to your credit file through a rent-reporting service.
Some services work with landlords or tenants to report regular rent payments to credit reference agencies.
This may help demonstrate a history of making rent payments on time.
However, the effect depends on the service, the credit reference agency receiving the information and the lender’s assessment process.
Before signing up, check:
- Whether the service is free or paid
- Which credit reference agencies receive the information
- How your data will be used
- Whether missed rent payments could also be reported
- The terms for cancelling the service
Do not assume that rent reporting will automatically increase your score or guarantee loan approval.
13. Avoid Unnecessary Financial Products
You may see advertisements for products that claim to improve your credit score quickly.
Some credit-building products may be useful in certain situations, but others can involve high interest rates, fees or unnecessary borrowing.
Before using any product, ask yourself:
- Do I really need it?
- Is the provider properly authorised where required?
- What are the interest rates and fees?
- Can I afford the repayments?
- Is there a free alternative?
Avoid credit repair companies that promise guaranteed results or claim they can erase accurate negative information.
You can check and manage much of your credit information yourself for free.
14. Be Patient: Credit Score Improvement Takes Time
Improving your credit profile is usually a gradual process.
Some changes, such as correcting an address or updating an account balance, may appear after the relevant information provider updates the credit reference agency.
Other negative information can remain on your report for several years.
For example, missed payments and defaults generally remain on a UK credit report for six years, although their impact may change over time.
There is no guaranteed timeline for improving your score.
Focus on consistent habits rather than expecting an overnight improvement.
15. Protect Yourself from Identity Theft and Credit Fraud
Fraudulent applications or accounts can damage your credit history and create financial problems.
Check your credit reports for unfamiliar accounts, searches or financial agreements.
If you notice something suspicious:
- Contact the relevant lender immediately.
- Contact the credit reference agency.
- Report suspected identity fraud to the appropriate authorities.
- Change passwords for affected accounts.
- Keep records of your communications and evidence.
You can also contact Cifas for information about fraud prevention and Protective Registration if you believe you may be at risk of identity fraud.
Never share banking passwords, one-time passcodes or sensitive account information with someone claiming they can repair your credit score.
16. How Long Does It Take to Improve a Credit Score in the UK?
There is no fixed time in which every person will see an improvement.
The time depends on the reason your score is low and how quickly new information is reported.
For example:
- Correcting an address may help update your identity information.
- Reducing credit card balances may be reflected after the lender reports the new balance.
- Building a consistent payment history takes time.
- Accurate missed payments and defaults generally remain on reports for six years.
Remember that credit reference agencies update their information at different times.
Your score may change at one agency before another agency updates its records.
17. Frequently Asked Questions (FAQs)
Q1. How can I improve my credit score quickly in the UK?
Start by checking your credit reports, correcting errors, updating your address, paying bills on time and reducing high credit card balances. There is no guaranteed quick fix.
Q2. What is a good credit score in the UK?
There is no single UK-wide credit score range. Experian, Equifax and TransUnion use different scoring systems, so a good score on one agency’s scale may not match another agency’s scale.
Q3. Can I check my credit score for free in the UK?
Yes. You can access free credit report options and statutory reports from the credit reference agencies. Some services also provide a free score.
Q4. Does checking my own credit score reduce it?
No. Checking your own credit report is generally recorded as a soft search and does not negatively affect your credit score.
Q5. Does registering to vote improve my credit score?
Being registered at your current address can help lenders verify your identity and address. It may also help your credit profile, depending on the agency’s scoring system.
Q6. How long do missed payments stay on a UK credit report?
Missed payments generally remain on a credit report for six years. Their effect may reduce over time, but accurate information cannot usually be removed simply because you want a higher score.
Q7. Does having a credit card improve your credit score?
A credit card may help you build a repayment history if you use it responsibly and make payments on time. However, applying for a card you cannot afford may create financial problems.
Q8. Does my salary affect my credit score?
Your salary is not generally recorded as a direct credit score factor in the same way as payment history. However, lenders may consider your income and affordability when deciding whether to offer credit.
Q9. Can I get a loan with a poor credit score in the UK?
Some lenders may consider applicants with a poor credit history, but approval is not guaranteed. Rates and fees may be higher. Compare the total cost carefully and avoid unaffordable borrowing.
Q10. Can a credit repair company remove negative information?
A company cannot legitimately remove accurate negative information simply to improve your score. Incorrect information can be challenged through the credit reference agency and the organisation that supplied it.
Conclusion
Improving your credit score in the UK requires patience, regular monitoring and responsible financial habits.
Start by checking your credit reports with the main credit reference agencies. Correct any errors, keep your address details updated, pay bills on time and manage your existing borrowing carefully.
Avoid unnecessary credit applications and be cautious of companies promising instant credit score improvements.
Most importantly, remember that your credit score is only one part of a lender’s decision. Affordability, income, existing commitments and individual lending criteria can also matter.
By following these practical steps consistently, you can build a stronger credit history and improve your chances of accessing suitable financial products in the future.
Disclaimer: This article is for educational and informational purposes only. It is not personalised financial or credit advice. Credit scoring methods and lender requirements vary. Check your credit reports and consult official sources before making financial decisions.