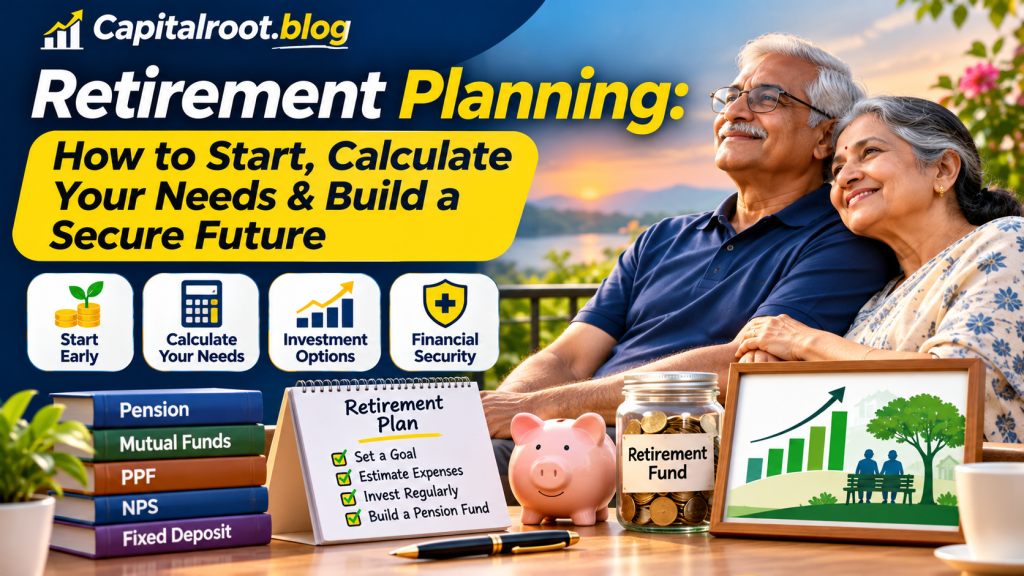

Retirement may seem far away when you are young and working, but the financial decisions you make today can have a major impact on your future lifestyle.
After retirement, regular salary income may stop or reduce. However, everyday expenses such as food, housing, healthcare, transportation, and family responsibilities continue.
This is why Retirement Planning is an important part of personal finance.
Retirement planning means preparing financially for the years when you may no longer want or be able to work full-time. It involves estimating future expenses, building savings, investing for long-term goals, understanding pension benefits, and managing financial risks.
Whether you are a salaried employee, self-employed professional, business owner, or freelancer, starting early can give your savings more time to grow.
In this guide, we will explain how retirement planning works, how much money you may need, which factors to consider, and how people in India, the USA, and the UK can prepare for retirement.
What Is Retirement Planning?
Retirement planning is the process of preparing your finances for life after regular employment.
It involves creating a long-term strategy to make sure you have enough income and savings to meet your needs when you stop working.
A retirement plan may include:
- Regular savings and investments.
- Employer-sponsored pension benefits.
- Government retirement benefits.
- Personal pension or retirement accounts.
- Healthcare and insurance planning.
- Debt repayment.
- Estate and inheritance planning.
The main goal is to build enough financial resources to support your lifestyle during retirement without depending entirely on other people.
Why Is Retirement Planning Important?
Retirement planning is important because your financial needs do not disappear when you stop working.
Here are some major reasons to start preparing early.
1. Financial Independence
A well-planned retirement can help you manage your expenses without depending completely on family members or other sources of support.
2. Protection Against Inflation
The cost of food, healthcare, housing, and other essential services may increase over time.
Money that seems sufficient today may not provide the same purchasing power after 20 or 30 years.
Investing and reviewing your retirement plan can help you prepare for rising costs.
3. Healthcare Expenses
Healthcare needs may increase with age. Medical treatment, medicines, hospitalisation, and long-term care can create significant expenses.
Retirement planning should include a separate strategy for healthcare costs.
4. Longer Life Expectancy
People may live for many years after leaving full-time employment.
Your retirement savings may need to support you for two or three decades or even longer.
5. Maintaining Your Lifestyle
If you want to travel, pursue hobbies, support family members, or enjoy a comfortable lifestyle after retirement, you need to plan for those expenses in advance.
6. Reducing Financial Stress
Having a retirement plan can provide greater clarity about your future income, savings, and financial responsibilities.
It can also help you identify gaps while you still have time to make changes.
When Should You Start Retirement Planning?
The best time to start retirement planning is generally as early as you reasonably can.
Starting early gives your savings more time to benefit from compounding and long-term investment growth.
However, it is never too late to begin.
Here is a general approach for different age groups.
In Your 20s: Build the Foundation
Your 20s are a useful time to develop good financial habits.
You can:
- Start saving a small amount regularly.
- Learn about pension and retirement accounts.
- Build an emergency fund.
- Avoid unnecessary high-interest debt.
- Understand basic investment risks.
- Increase savings as your income grows.
You do not need a large amount to begin. Consistency matters.
In Your 30s: Increase Contributions
During your 30s, your income and responsibilities may increase.
This is a good time to review your retirement goals and increase your contributions when possible.
You should also consider employer pension benefits, insurance needs, and long-term financial commitments.
In Your 40s: Review Your Progress
By your 40s, you may have a clearer understanding of your expected retirement lifestyle.
Review your savings, investments, debts, and projected retirement income.
If you are behind your target, consider increasing contributions or adjusting your retirement timeline.
In Your 50s: Prepare for Retirement
During your 50s, focus on understanding how much retirement income you may receive and when you can access it.
Review investment risk, healthcare arrangements, outstanding loans, and your expected retirement expenses.
Avoid making rushed investment decisions simply because retirement is approaching.
In Your 60s and Beyond: Plan Withdrawals
If you are close to retirement, focus on managing your existing savings and creating a sustainable withdrawal strategy.
Consider regular income needs, taxes, healthcare, inflation, and how long your money may need to last.
How Much Money Do You Need for Retirement?
One of the most common retirement questions is: How much money will I need after I stop working?
There is no single amount that works for everyone.
Your retirement target depends on several factors:
- Your current age.
- Your expected retirement age.
- Current monthly expenses.
- Expected inflation.
- Healthcare requirements.
- Housing costs.
- Existing savings and investments.
- Pension and government benefits.
- Expected retirement duration.
- Desired lifestyle.
Example of a Retirement Expense Calculation
Suppose your current monthly household expenses are ₹40,000.
If you expect to retire after 20 years and assume average annual inflation of 6%, the estimated monthly expense at retirement would be approximately ₹1,28,000.
This is an illustration, not a prediction of future inflation or a guaranteed expense figure.
It shows why simply multiplying today’s monthly expenses by 12 may underestimate future retirement needs.
Basic Retirement Planning Formula
You can begin with a simple framework:
Estimated Retirement Corpus = Expected Annual Retirement Expenses × Estimated Retirement Years
For example, if your estimated annual retirement expenses are ₹15 lakh and you plan for 25 years of retirement:
₹15,00,000 × 25 = ₹3,75,00,000
This simple calculation gives a starting point, not a complete retirement target. It does not account for investment returns, inflation during retirement, taxes, pension income, or changes in spending.
A more detailed plan should consider these factors and the timing of withdrawals.
Important Factors That Affect Your Retirement Corpus
Your retirement target can change significantly depending on your personal circumstances.
1. Retirement Age
Retiring earlier generally means you need to fund more years without employment income.
Working longer may allow additional contributions and reduce the number of years your savings must support.
2. Inflation
Inflation reduces the purchasing power of money over time.
A retirement plan should use realistic inflation assumptions rather than assuming today’s expenses will remain unchanged.
3. Healthcare Costs
Medical expenses can be unpredictable.
Consider health insurance, out-of-pocket costs, and possible long-term care requirements.
4. Investment Returns
Your retirement savings may grow through interest, dividends, and investment returns.
However, returns are not guaranteed, and market-linked investments can lose value.
5. Pension and Other Income
Your required personal savings may be lower if you expect reliable pension income, government benefits, rental income, or other sources of retirement income.
6. Family Responsibilities
You may need to support children, parents, or other family members.
Include these possible responsibilities when estimating your retirement budget.
Best Retirement Savings and Investment Options
There are different ways to prepare for retirement. The right options depend on your country, age, financial goals, risk tolerance, and eligibility.
1. Employer-Sponsored Retirement Plans
Some employers provide pension or retirement savings benefits.
These plans may include employer contributions, employee contributions, or a defined pension based on salary and years of service.
Understand the contribution rules, investment choices, fees, and withdrawal conditions.
2. Government Pension Schemes
Some countries provide government-supported retirement benefits.
Eligibility, contribution requirements, and benefit amounts depend on local rules and your work history.
Do not assume that government benefits alone will cover all your retirement expenses.
3. Personal Pension Plans
Personal pension products allow individuals to save for retirement outside an employer-sponsored plan.
The tax treatment, contribution limits, and withdrawal rules vary by country.
4. Mutual Funds and ETFs
Mutual funds and exchange-traded funds (ETFs) can provide exposure to different asset classes.
Some investors use diversified funds as part of a long-term retirement portfolio.
However, market-linked investments involve risk, and their value can rise or fall.
5. Bonds and Fixed-Income Investments
Bonds and certain fixed-income products may provide interest income and help balance a portfolio.
They still carry risks, including interest-rate risk, inflation risk, and credit risk.
6. Real Estate
Some people include property in their long-term retirement strategy.
Rental income may provide an additional source of cash flow, but property can involve maintenance costs, vacancies, taxes, and limited liquidity.
7. Cash and Savings
Cash and savings accounts can help meet short-term needs and unexpected expenses.
However, keeping all retirement money in cash may expose your savings to inflation risk over long periods.
A diversified plan may combine different types of assets.
How to Create a Retirement Plan Step by Step
You do not need to create a complicated financial strategy on the first day.
Start with these practical steps.
Step 1: Decide Your Retirement Age
Choose an approximate age at which you would like to stop working full-time.
Your target age will help determine how many years you have to save and how long your savings may need to last.
Step 2: Estimate Your Future Expenses
List your expected retirement expenses, including:
- Housing and maintenance.
- Food and groceries.
- Healthcare and medicines.
- Transportation.
- Utilities and bills.
- Travel and entertainment.
- Family responsibilities.
- Taxes and insurance.
Separate essential expenses from optional lifestyle expenses.
Step 3: Calculate Your Existing Retirement Resources
List your current savings, pension balances, employer contributions, investments, and other expected income sources.
Use updated statements instead of rough guesses.
Step 4: Identify the Retirement Savings Gap
Compare your expected retirement resources with your estimated future needs.
If there is a shortfall, determine how much additional saving or investing may be required.
Step 5: Choose Suitable Savings and Investment Options
Select products based on your time horizon, risk tolerance, fees, tax treatment, and local rules.
Avoid investing in products you do not understand.
Step 6: Automate Contributions
Where possible, set up regular contributions to eligible retirement or investment accounts.
Automatic contributions can help you maintain consistency.
Step 7: Review Your Plan Regularly
Review your retirement plan at least once a year and whenever your income, family situation, health, or financial goals change.
Retirement Planning in India
India offers several retirement savings and pension options. Their suitability depends on employment status, age, eligibility, tax rules, and individual financial goals.
National Pension System (NPS)
The National Pension System is a defined-contribution retirement system regulated by the Pension Fund Regulatory and Development Authority (PFRDA).
It allows eligible individuals to contribute towards long-term retirement savings. Contributions are invested in market-linked options according to the selected allocation and applicable rules.
NPS offers flexibility and portability, but investment returns are not guaranteed.
Check the latest contribution, exit, annuity, and tax rules through the official PFRDA and NPS websites.
Employees’ Provident Fund (EPF)
The Employees’ Provident Fund is a retirement savings arrangement for eligible employees covered by the applicable EPF rules.
Both employees and employers may contribute according to the scheme’s rules.
Check your EPF passbook and official Employees’ Provident Fund Organisation (EPFO) guidance to understand your balance and withdrawal conditions.
Public Provident Fund (PPF)
The Public Provident Fund is a government-backed long-term savings scheme available to eligible individuals under its rules.
It has a specified maturity period, contribution conditions, and tax treatment.
Before investing, check the latest official interest rate, contribution limits, and withdrawal rules.
Atal Pension Yojana (APY)
Atal Pension Yojana is a government-backed pension scheme designed for eligible subscribers, particularly in the unorganised sector.
Eligibility and joining conditions apply. The scheme has age-related and contribution requirements, so check the latest rules before enrolling.
Retirement Planning Tips for India
- Review your EPF balance and employment history.
- Understand NPS and other eligible pension options.
- Check PPF contribution and maturity rules.
- Estimate healthcare and family expenses.
- Review tax treatment before choosing a product.
- Avoid relying entirely on one retirement investment.
Retirement Planning in the USA
In the United States, retirement planning often combines employer-sponsored plans, individual retirement accounts, and Social Security benefits.
401(k) Plans
A 401(k) is an employer-sponsored retirement savings plan.
Employees can contribute a portion of their eligible compensation, and some employers may provide matching contributions.
Traditional and Roth 401(k) options have different tax treatments.
Review your employer’s plan rules, investment choices, fees, and matching contribution policy.
Individual Retirement Accounts (IRAs)
An Individual Retirement Account (IRA) is a personal retirement savings account.
Traditional and Roth IRAs have different contribution and tax rules.
Eligibility, contribution limits, and withdrawal conditions can change, so check current IRS guidance before making decisions.
Social Security Benefits
Social Security provides retirement benefits to eligible workers based on their earnings history and other rules.
The age at which you claim benefits can affect the amount you receive.
Use the official Social Security Administration tools to review your estimated benefits and understand your full retirement age.
Retirement Planning Tips for the USA
- Review your 401(k) contributions.
- Understand whether your employer offers matching contributions.
- Compare traditional and Roth retirement account rules.
- Check your Social Security benefit estimate.
- Review investment fees and diversification.
- Consider healthcare costs and Medicare eligibility.
Retirement Planning in the UK
The UK retirement system includes the State Pension, workplace pensions, and personal pension arrangements.
State Pension
The UK State Pension provides retirement income to eligible individuals based on their National Insurance record and applicable rules.
Check your State Pension forecast to understand your expected entitlement and when you can claim it.
Workplace Pensions
Eligible employees are generally automatically enrolled into a workplace pension scheme, subject to the relevant conditions.
Both employees and employers may contribute.
Review your pension statement to understand contributions, investment choices, fees, and projected retirement income.
Personal Pensions and SIPPs
Individuals may also use personal pension products.
A Self-Invested Personal Pension (SIPP) provides investment choice within a pension wrapper, subject to UK pension rules.
Before selecting a pension product, compare charges, investment options, tax treatment, and access conditions.
Retirement Planning Tips for the UK
- Check your State Pension forecast.
- Review your workplace pension statements.
- Find any old or lost pension accounts.
- Understand pension tax relief and withdrawal rules.
- Use an official pension calculator.
- Consider regulated financial advice for complex decisions.
Common Retirement Planning Mistakes to Avoid
Even people who save regularly can make mistakes that affect their future financial security.
1. Starting Too Late
Delaying retirement savings reduces the time available for contributions and potential compounding.
Start with an affordable amount rather than waiting until you can invest a large sum.
2. Underestimating Inflation
Ignoring inflation can make your retirement target too small.
Review your expense assumptions regularly.
3. Ignoring Healthcare Costs
Medical and long-term care expenses can place pressure on retirement savings.
Include healthcare planning in your overall strategy.
4. Depending Only on Government Benefits
Government pension or Social Security benefits may not fully cover your desired lifestyle.
Understand your expected benefits and plan for any income gap.
5. Taking Too Much Investment Risk
Chasing high returns can expose retirement savings to unnecessary losses.
Choose investments according to your time horizon and ability to handle risk.
6. Ignoring Fees and Taxes
Investment fees and taxes can reduce the amount available for retirement.
Understand the total cost and tax treatment of each product.
7. Not Reviewing Your Plan
Your income, expenses, health, and family responsibilities may change over time.
Review your plan regularly and update it when necessary.
8. Withdrawing Retirement Savings Too Early
Early withdrawals may reduce your future retirement income and can trigger taxes or penalties depending on the account and country.
Understand the rules before withdrawing.
How to Prepare for Retirement if You Start Late
If you are in your 40s or 50s and have not saved enough, do not panic.
You can still take practical steps to improve your financial position.
- Calculate your current savings and expected pension income.
- Review your monthly expenses and identify unnecessary spending.
- Increase retirement contributions when your budget allows.
- Consider working longer if it is practical.
- Review outstanding debts and repayment plans.
- Avoid speculative investments that promise quick returns.
- Understand your government and employer pension benefits.
- Seek qualified financial advice if your retirement situation is complex.
The goal is to make informed improvements rather than take unnecessary risks to recover lost time.
Retirement Planning Checklist
Use this checklist to review your financial preparation.
-
Decide your approximate retirement age.
-
Estimate your future monthly expenses.
-
Calculate your existing retirement savings.
-
Check employer and government pension benefits.
-
Review your health insurance arrangements.
-
Understand investment risks and fees.
-
Set a regular contribution target.
-
Review outstanding debts.
-
Check beneficiary and nomination details.
-
Review your retirement plan every year.
Frequently Asked Questions (FAQs)
1. What is retirement planning?
Retirement planning is the process of preparing financially for life after full-time employment. It includes savings, investments, pension benefits, expense estimates, and long-term income planning.
2. At what age should I start retirement planning?
You can start as soon as you begin earning, but it is never too late. Starting early gives your savings more time to grow.
3. How much money do I need for retirement?
The amount depends on your future expenses, retirement age, inflation, healthcare needs, pension income, and expected retirement duration. There is no single target suitable for everyone.
4. What is the best investment for retirement?
There is no universally best investment. Retirement plans may include pension accounts, diversified funds, bonds, fixed-income products, and other eligible investments depending on your circumstances and risk tolerance.
5. Is NPS useful for retirement planning in India?
NPS is one of the retirement savings options available in India. It offers market-linked investment choices and is regulated by PFRDA. Understand its contribution, investment, exit, and annuity rules before joining.
6. What is the difference between a pension and retirement savings?
A pension generally refers to a retirement income arrangement, while retirement savings can include money accumulated through pension accounts, investments, and other financial assets.
7. Can self-employed people plan for retirement?
Yes. Self-employed people can create their own retirement strategy through eligible pension products, long-term investments, and regular savings contributions.
8. What happens if I start retirement planning late?
Starting late may require higher contributions, lower expected spending, a later retirement date, or a combination of these. A realistic review can help you identify practical options.
9. Should I pay off debt before retirement?
Reducing high-interest debt before retirement can improve cash flow and reduce financial pressure. However, the right repayment strategy depends on interest rates, available savings, and other obligations.
10. How often should I review my retirement plan?
Review it at least once a year and whenever you experience major changes in income, expenses, employment, family responsibilities, or health.
11. Does retirement planning include healthcare?
Yes. Healthcare costs, insurance coverage, medicines, and possible long-term care should be included in retirement planning.
12. Can I retire early?
Early retirement may be possible if you have sufficient assets and income to support your expected expenses for a longer period. Consider healthcare, taxes, pension access rules, and inflation before deciding.
Conclusion
Retirement planning is not just about saving money. It is about creating a financial strategy that can support your lifestyle, healthcare needs, and personal goals after regular employment ends.
Starting early, contributing consistently, understanding pension benefits, and reviewing your investments can help you prepare for the future.
If you have not started yet, begin by estimating your expenses and reviewing your existing financial resources. Even small, consistent steps can make a difference over time.
Remember that a good retirement plan should match your age, income, country, risk tolerance, and long-term needs. Review it regularly and make changes as your circumstances evolve.