
When you apply for a personal loan, home loan, car loan, or mortgage, lenders do not look only at your salary. They also want to understand how much of your income is already being used to repay existing debts.
This is where the Debt-to-Income Ratio (DTI) becomes important.
DTI is a financial measure that compares your monthly debt payments with your monthly income. It helps lenders assess whether you can comfortably manage another loan repayment.
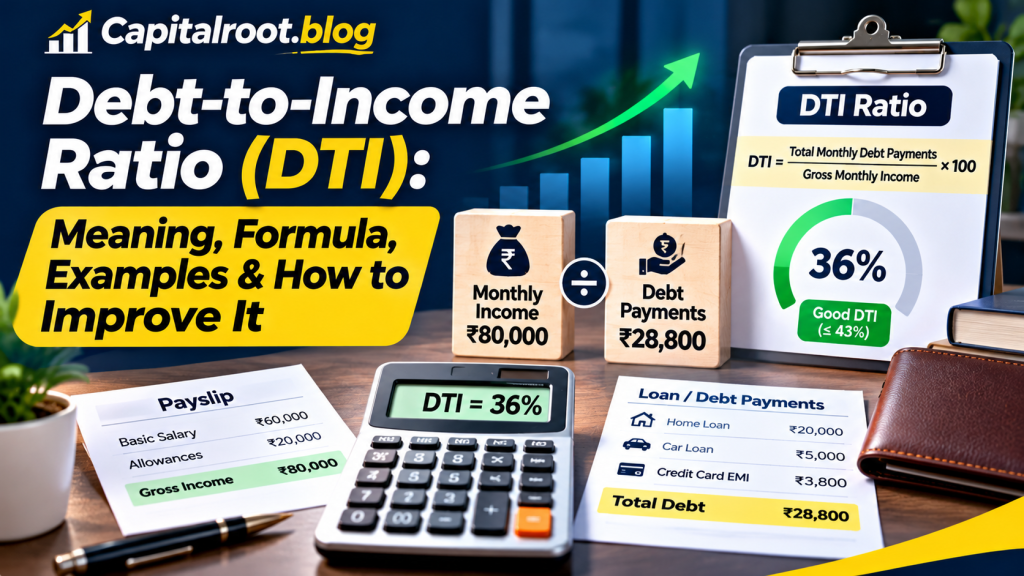
For example, if you earn ₹80,000 per month and pay ₹28,800 towards existing monthly debts, your DTI is 36%.
A lower DTI generally indicates that you have more income available to manage additional repayments. However, lenders consider other factors too, including your credit history, employment, expenses, and loan amount.
In this guide, you will learn what DTI means, how to calculate it, what different DTI levels indicate, how lenders use it, and practical ways to improve it before applying for a loan.
What Is a Debt-to-Income Ratio?
A Debt-to-Income Ratio is the percentage of your gross monthly income that goes towards paying your monthly debt obligations.
In simple words, it shows how much of your income is already committed to repaying loans and other qualifying debts.
For example:
-
Monthly gross income: ₹80,000
-
Monthly loan and debt payments: ₹28,800
-
Debt-to-income ratio: 36%
This means 36% of your gross monthly income is being used for debt payments.
Lenders may use DTI as one part of their loan affordability assessment. It helps them understand whether a borrower may be able to manage additional repayments without becoming financially overstretched.
Important: DTI is not the same as your credit score. A credit score reflects aspects of your credit history, while DTI compares debt payments with income.
What Is the DTI Formula?
The standard DTI calculation is straightforward.
DTI Formula:
DTI = (Total Monthly Debt Payments ÷ Gross Monthly Income) × 100
Where:
-
Total Monthly Debt Payments: Your qualifying monthly loan and debt obligations.
-
Gross Monthly Income: Your income before tax and other deductions, when using the common gross-income DTI method.
Example of DTI Calculation
Suppose a person earns ₹80,000 per month before deductions and has the following monthly payments:
| Monthly Debt | Amount |
|---|---|
| Home loan EMI | ₹20,000 |
| Car loan EMI | ₹5,000 |
| Personal loan EMI | ₹2,500 |
| Credit card required payment | ₹1,300 |
| Total Monthly Debt | ₹28,800 |
Now apply the formula:
DTI = (₹28,800 ÷ ₹80,000) × 100
DTI = 36%
This means the person uses 36% of their gross monthly income for the listed debt payments.
The remaining 64% is not automatically disposable income. It may still need to cover taxes, rent if not included in debt payments, groceries, utilities, insurance, transport, savings, and other living expenses.
How to Calculate Your DTI Step by Step
You can calculate your DTI yourself before applying for a loan.
Step 1: Calculate Your Gross Monthly Income
Add your regular income before tax and other deductions.
Depending on the lender’s rules, eligible income may include:
-
Monthly salary.
-
Regular business income.
-
Self-employment income.
-
Rental income.
-
Other verifiable recurring income.
Do not include uncertain or irregular income unless the lender accepts it.
Step 2: List Your Monthly Debt Payments
Write down the required monthly payments for your existing debts.
These may include:
-
Home loan or mortgage payments.
-
Personal loan EMIs.
-
Car loan payments.
-
Student loan repayments.
-
Credit card required payments.
-
Other qualifying debt obligations.
The exact debts included depend on the lender’s calculation method.
Step 3: Add All Monthly Debt Payments
Calculate the total amount you pay towards qualifying debts each month.
Step 4: Divide Debt Payments by Gross Income
Divide your total monthly debt payments by your gross monthly income.
Step 5: Multiply by 100
Multiply the result by 100 to get your DTI percentage.
You can now use this percentage to understand how much of your income is committed to debt repayment.
What Is a Good Debt-to-Income Ratio?
A lower DTI is generally more favourable because it indicates that a smaller share of your income is committed to existing debts.
However, there is no single DTI percentage that guarantees loan approval across all countries, banks, or loan products.
The following table is a general educational guide, not a universal lender rule.
| DTI Range | General Interpretation |
|---|---|
| Below 20% | Relatively low debt burden |
| 20%–35% | Often manageable, depending on expenses |
| 36%–43% | Higher debt commitment; affordability needs review |
| 44%–50% | Significant debt burden |
| Above 50% | High debt commitment and potentially limited borrowing capacity |
Your actual loan eligibility depends on the lender’s criteria, income stability, credit history, loan type, household expenses, and other financial factors.
A borrower with a higher DTI may still qualify for some products, while another borrower with a lower DTI may be declined for different reasons.
Why Do Lenders Check Your DTI Ratio?
Lenders use DTI as one of several tools to assess whether a borrower can manage loan repayments.
1. To Understand Repayment Capacity
A lender wants to know whether you have enough income to meet your existing obligations and the proposed new EMI.
2. To Assess Loan Affordability
Your DTI helps lenders estimate how much of your income is already committed to debt.
3. To Evaluate Financial Risk
A high DTI may indicate that you have limited room to manage another repayment, especially if your income changes or unexpected expenses arise.
4. To Decide Loan Amounts
DTI may influence how much a lender is willing to offer, along with other eligibility factors.
5. To Review Mortgage Applications
Mortgage lenders often examine existing debt payments and the proposed housing payment when assessing affordability.
6. To Support Responsible Lending
Assessing income and existing obligations helps lenders make more informed lending decisions.
Factors That Affect Your Debt-to-Income Ratio
Several factors can increase or decrease your DTI.
1. Monthly Loan EMIs
Higher monthly loan payments increase your total debt obligations and can raise your DTI.
2. Credit Card Payments
Required credit card payments may be included in a lender’s calculation. The method can vary by lender and country.
3. Monthly Income
A higher eligible income can reduce your DTI if your debt payments remain unchanged.
4. Multiple Loans
Having several active loans may increase your total monthly repayment burden.
5. Student Loan Payments
Student loan repayments may be included when a lender calculates your qualifying monthly debt.
6. Income Stability
Stable and verifiable income may strengthen an overall loan application, even though income stability itself is not part of the DTI formula.
7. New Loan Applications
A new loan can increase your monthly obligations if approved and taken. Multiple applications may also affect your credit profile depending on the credit reporting system.
DTI vs Credit Score: What Is the Difference?
DTI and credit score are both important in lending, but they measure different things.
| Feature | Debt-to-Income Ratio | Credit Score |
|---|---|---|
| Measures | Debt payments compared with income | Credit history and repayment behaviour |
| Main purpose | Assesses repayment affordability | Assesses credit risk |
| Calculation | Monthly debts ÷ gross monthly income | Based on credit bureau data and scoring models |
| Changes when | Income or monthly debt obligations change | Credit report information changes |
| Used by lenders | To evaluate affordability | To assess creditworthiness |
Can You Have a Good Credit Score but a High DTI?
Yes.
You may have a strong credit score because you have paid your loans on time for years. However, if you have several active loans and high monthly repayments, your DTI may still be high.
Similarly, someone may have a low DTI but a weak credit history.
This is why lenders generally consider multiple financial factors instead of relying on only one number.
What Is FOIR and How Is It Different from DTI?
In India, you may also come across the term Fixed Obligation to Income Ratio (FOIR).
FOIR is used by some lenders to evaluate how much of an applicant’s income is committed to existing fixed financial obligations.
A simplified FOIR calculation is:
FOIR = (Monthly Fixed Obligations ÷ Monthly Income) × 100
For example:
-
Monthly income: ₹60,000
-
Existing fixed monthly obligations: ₹24,000
FOIR = (₹24,000 ÷ ₹60,000) × 100
FOIR = 40%
DTI and FOIR are closely related concepts, but their definitions and calculation methods may differ between lenders.
Some lenders may use gross income, while others may assess net or eligible income. They may also treat household expenses, credit card obligations, and other commitments differently.
Always ask the lender how it calculates your repayment obligations.
How to Improve Your Debt-to-Income Ratio
If your DTI is high, you can take practical steps to reduce it.
1. Pay Off Smaller Existing Debts
If possible, clear smaller loans or outstanding balances that create monthly repayment obligations.
This may reduce your total monthly debt payments.
2. Avoid Taking Multiple Loans
Before applying for another loan, review whether you genuinely need it.
Taking several loans within a short period can increase your monthly financial burden.
3. Increase Your Income
You may improve your DTI by increasing your eligible income through:
-
Additional professional work.
-
Freelancing.
-
A salary increase.
-
A side business.
-
Other stable and verifiable income sources.
Only include income that the lender accepts for its assessment.
4. Reduce Credit Card Debt
Paying down credit card balances and avoiding unnecessary borrowing can help improve your overall financial position.
Check how your lender treats credit card payments in its DTI calculation.
5. Avoid Unnecessary Borrowing
Do not take a new loan simply because a lender offers it.
Borrow only when the repayment fits your budget and financial goals.
6. Review Your Monthly Budget
Track your income, essential expenses, loan payments, and savings.
A clear budget can help you identify areas where you can reduce spending and pay down debt.
7. Consider a Longer Loan Tenure Carefully
A longer repayment tenure may reduce the monthly EMI on some loans, which can lower the calculated DTI.
However, it may increase the total interest paid over the life of the loan.
Compare the total repayment cost before choosing a longer tenure.
8. Avoid Using All Your Available Credit
High credit card utilisation can affect your credit profile. Keep balances manageable and pay bills on time.
Remember that credit utilisation and DTI are different measures, even though both can matter to lenders.
How DTI Affects Different Types of Loans
DTI can influence different loan applications in different ways.
1. Personal Loans
Personal loan lenders may examine your existing EMIs and income to assess whether you can manage another monthly repayment.
A high DTI may reduce the loan amount offered or affect approval.
2. Home Loans
Home loan lenders consider your existing financial obligations along with the proposed home loan EMI.
Your income, employment, credit history, property value, loan tenure, and other factors also matter.
3. Car Loans
When applying for a car loan, lenders may review your existing debt payments to assess whether the additional EMI is affordable.
4. Student Loans
Student loan assessments vary depending on the country and loan programme. Some lenders may consider the applicant’s or co-signer’s existing financial obligations.
5. Credit Cards
Credit card issuers may evaluate income, existing obligations, credit history, and other risk factors before approving an application or setting a credit limit.
DTI Rules and Lending Practices in India, the USA and the UK
DTI calculations and lending practices are not identical across countries.
Debt-to-Income Ratio in India
Indian lenders may assess repayment capacity using income, existing EMIs, household expenses, and other financial commitments.
Some banks and financial institutions use FOIR or similar internal affordability measures.
Before applying for a loan in India:
-
Check your existing monthly EMIs.
-
Review your salary or business income.
-
Include other fixed financial commitments.
-
Ask the lender how it calculates FOIR or repayment capacity.
-
Compare the proposed EMI with your monthly budget.
-
Review the loan’s interest rate and total repayment amount.
The Reserve Bank of India provides guidance on responsible lending and borrower creditworthiness. Its rules for specific lending categories should not be confused with one universal DTI threshold for every loan.
Debt-to-Income Ratio in the USA
In the United States, DTI is commonly used in mortgage lending.
It is generally calculated by dividing qualifying monthly debt payments by gross monthly income.
Mortgage lenders may consider:
-
Housing payments.
-
Car loan payments.
-
Student loan repayments.
-
Credit card obligations.
-
Other qualifying recurring debts.
Different loan programmes and lenders have different DTI requirements.
For example, Fannie Mae’s selling guide describes DTI calculation and underwriting requirements for loans eligible for its programmes. These rules do not automatically apply to every US lender or mortgage product.
Debt-to-Income Ratio in the UK
In the United Kingdom, lenders commonly conduct affordability assessments before approving borrowing.
They may consider:
-
Income and employment.
-
Existing credit commitments.
-
Housing costs.
-
Household expenses.
-
Regular financial commitments.
-
Whether repayments remain affordable under different circumstances.
There is no single universal DTI threshold that guarantees approval for every UK loan.
Lenders use their own assessment methods while following applicable regulatory requirements.
Common Mistakes to Avoid When Calculating DTI
Avoid these mistakes when working out your DTI.
1. Using Take-Home Salary Without Checking the Method
The common DTI formula uses gross monthly income, but some lenders may use different income measures.
Use the method specified by your lender when assessing eligibility.
2. Forgetting Existing Loan Payments
Include all relevant monthly debt obligations rather than calculating only one or two EMIs.
3. Ignoring Credit Card Obligations
Check whether required credit card payments or other revolving credit obligations are included.
4. Treating All Income as Guaranteed
Do not rely on uncertain bonuses or irregular income unless the lender accepts them.
5. Assuming a Low DTI Guarantees Approval
A low DTI does not guarantee approval. Credit history, income verification, loan purpose, employment, and other criteria still matter.
6. Confusing DTI with Credit Utilisation
DTI compares debt payments with income. Credit utilisation compares revolving credit balances with available credit limits.
They are not the same calculation.
Practical Tips Before Applying for a Loan
Use this checklist before submitting a loan application:
-
Calculate your current DTI.
-
Check your credit report for errors.
-
List all active loans and monthly repayments.
-
Estimate the EMI of the new loan.
-
Calculate your DTI after adding the proposed EMI.
-
Review your essential monthly expenses.
-
Keep some room in your budget for unexpected costs.
-
Compare loan interest rates and total repayment costs.
-
Check all processing fees and other charges.
-
Borrow only an amount you can comfortably repay.
Frequently Asked Questions (FAQs)
1. What is a good debt-to-income ratio?
A lower DTI is generally better because it means a smaller share of your income is committed to debt payments. However, acceptable limits vary by lender, loan type, and country.
2. How do I calculate my DTI?
Add your qualifying monthly debt payments, divide the total by your gross monthly income, and multiply the result by 100.
3. Is a 40% DTI good?
A 40% DTI may be acceptable for some loan products and lenders, while others may require a lower ratio. It is not a universal approval standard.
4. Does DTI affect personal loan approval?
Yes. Some lenders use DTI or similar affordability measures to assess whether applicants can manage additional loan payments.
5. Can I get a loan with a high DTI?
It may be possible, depending on the lender’s criteria, your income, credit history, loan type, and other financial factors. A high DTI may reduce your borrowing options.
6. Does DTI include rent?
It depends on the lender’s calculation method and loan type. Mortgage underwriting may treat housing costs separately or include them in a broader affordability assessment.
7. Does DTI include credit card debt?
Many lenders include required credit card payments or calculate an obligation based on the outstanding balance. The exact method varies.
8. What is the difference between DTI and FOIR?
DTI is commonly used to compare monthly debt payments with gross monthly income. FOIR is a measure used by some Indian lenders to assess fixed financial obligations against income. Their exact calculation methods may differ.
9. Can increasing my income improve my DTI?
Yes. If your eligible income increases while your monthly debt payments remain unchanged, your DTI will decrease.
10. Does paying off a loan improve DTI?
It can. If paying off a loan removes a qualifying monthly repayment obligation, your DTI may decrease. Check that the lender has updated the relevant account information.
11. Is DTI the same as a credit score?
No. DTI measures debt payments relative to income, while a credit score reflects information from your credit history.
12. Do all banks use the same DTI limit?
No. Banks and financial institutions use different lending criteria depending on the country, loan product, applicant profile, and regulatory requirements.
Conclusion
The Debt-to-Income Ratio is an important measure that helps borrowers understand how much of their income is already committed to monthly debt payments.
It is also one of the factors lenders may use when assessing personal loans, home loans, car loans, and mortgages.
Calculating your DTI before applying for a loan can help you understand your repayment capacity and avoid taking on more debt than your budget can comfortably support.
If your DTI is high, consider reducing existing debts, avoiding unnecessary borrowing, increasing eligible income, and reviewing your monthly budget.
Remember that a good DTI alone does not guarantee loan approval. Lenders also consider credit history, income stability, expenses, and other eligibility requirements.