
Your CIBIL score is an important part of your financial profile. Whether you want to apply for a personal loan, home loan, car loan or credit card, lenders may check your credit history and score while evaluating your application.
A good credit score can improve your chances of getting a loan and may help you qualify for more favourable lending terms. On the other hand, a low score, missed payments or excessive outstanding debt can make borrowing more difficult.
The good news is that you can improve your credit profile by developing responsible financial habits. Paying EMIs on time, keeping credit card balances under control and checking your credit report regularly are some of the most useful steps.
In this guide, we will explain how to improve your CIBIL score in India, understand the factors affecting it and explore practical ways to build a healthier credit history.
1. What Is a CIBIL Score?
A CIBIL score is a three-digit number that represents your credit history and credit behaviour. It is calculated by TransUnion CIBIL using information available in your credit report.
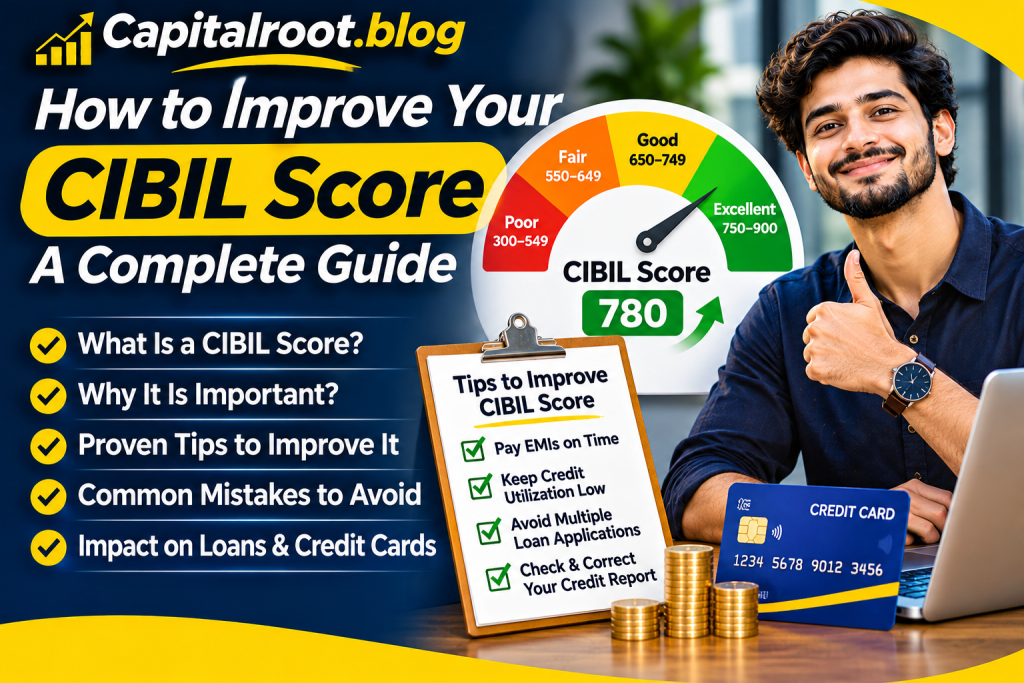
The score generally ranges from 300 to 900.
A higher score generally indicates a stronger credit history, while a lower score may indicate a higher credit risk.
Lenders use credit information as one factor when evaluating loan and credit card applications. However, the CIBIL score alone does not guarantee approval or rejection. Lenders also consider income, employment, existing obligations, repayment capacity and their own eligibility policies.
2. What Is a Good CIBIL Score in India?
CIBIL scores range from 300 to 900. A higher score is generally more favourable when lenders assess credit applications.
The following table is a simplified guide, not an official universal classification used by every lender.
| CIBIL Score | General Interpretation |
|---|---|
| 300–549 | Low score; credit applications may be difficult |
| 550–649 | Below average; improvement may be needed |
| 650–699 | Fair; lenders may assess applications carefully |
| 700–749 | Good; generally a stronger credit profile |
| 750–900 | Very strong; generally favourable credit history |
Many borrowers aim for a score of 750 or above, but different lenders have different eligibility criteria. A score above 750 does not guarantee the lowest interest rate or loan approval.
3. Understand the Factors That Affect Your CIBIL Score
Before improving your score, understand what influences it.
A. Payment History
Your payment history is an important part of your credit profile.
Late EMI payments, missed credit card bills and overdue amounts can negatively affect your score.
Paying your dues on time helps establish a responsible repayment history.
B. Credit Utilisation
Credit utilisation refers to the amount of your available credit limit that you are using.
For example, if your credit card limit is ₹1,00,000 and your outstanding balance is ₹70,000, your utilisation is 70%.
High utilisation may indicate that you are relying heavily on borrowed money.
Keeping utilisation low is generally a good credit habit. Some borrowers use 30% as a practical guideline, but it is not a guaranteed CIBIL scoring threshold.
C. Length of Credit History
The age of your credit accounts can also influence your credit profile.
A longer history of responsible borrowing can help demonstrate how consistently you manage credit.
Avoid closing older accounts without understanding the possible impact on your credit profile.
D. Credit Mix
Your credit profile may include secured and unsecured credit.
Examples include:
- Home loans.
- Car loans.
- Personal loans.
- Credit cards.
A healthy credit profile is not about borrowing as many types of loans as possible. Do not take unnecessary loans simply to create a credit mix.
E. New Credit Applications
When you apply for credit, a lender may make a hard enquiry on your credit report.
Making multiple applications within a short period can create several enquiries and may negatively affect your score.
Apply for credit only when you genuinely need it.
4. Pay Your EMIs and Credit Card Bills on Time
One of the most important habits for maintaining a healthy credit score is paying all credit obligations on time.
Even a small delay may be reported by a lender and affect your credit history.
Follow these steps:
- Note every EMI due date.
- Pay credit card bills before the due date.
- Maintain enough balance in your bank account for auto-debit payments.
- Set payment reminders.
- Check whether your payments have been credited successfully.
- Contact the lender promptly if a payment is incorrectly recorded.
If you have several loans, create a repayment calendar to avoid missing any due date.
Practical tip: Set reminders a few days before each due date instead of waiting until the last day.
5. Keep Your Credit Card Utilisation Low
Using a large portion of your available credit limit may make your credit profile appear more dependent on borrowing.
Consider this example:
| Credit Card Limit | Outstanding Balance | Utilisation |
|---|---|---|
| ₹50,000 | ₹10,000 | 20% |
| ₹50,000 | ₹20,000 | 40% |
| ₹50,000 | ₹35,000 | 70% |
| ₹50,000 | ₹45,000 | 90% |
Keeping your outstanding balance relatively low is generally a sensible habit.
You can manage utilisation by:
- Avoiding unnecessary purchases on credit.
- Paying balances regularly.
- Keeping spending within your repayment capacity.
- Requesting a credit limit review only if appropriate.
Do not spend more simply because your bank offers a higher credit limit.
6. Check Your CIBIL Report Regularly
Your credit report contains important information about your credit history.
It may include:
- Active loan accounts.
- Closed loan accounts.
- Credit card accounts.
- Payment history.
- Credit enquiries.
- Outstanding balances.
- Account status.
Review your report regularly to identify mistakes or suspicious activity.
For example, you may discover:
- A loan that you never took.
- A payment incorrectly shown as overdue.
- A closed loan still appearing as active.
- An incorrect outstanding balance.
- Duplicate account information.
You can access your credit information through the official TransUnion CIBIL website.
The RBI has directed credit information companies to provide individuals with one free full credit report, including the credit score, once every calendar year.
7. Correct Errors in Your CIBIL Report
Sometimes your credit report may contain incorrect information because of reporting or data-related issues.
If you find an error, raise a dispute with TransUnion CIBIL and contact the lender that reported the information.
Follow these steps:
- Obtain your latest credit report.
- Identify the incorrect account or payment entry.
- Collect supporting documents.
- Submit a dispute through the official credit bureau process.
- Contact the concerned bank or financial institution.
- Keep the complaint reference number.
- Follow up until the matter is resolved.
Remember that a credit bureau generally cannot independently change verified lender information without the required confirmation or correction from the reporting institution.
Do not pay an unknown agent who promises to remove genuine negative entries.
8. Avoid Applying for Multiple Loans at Once
Applying for several loans or credit cards within a short period can result in multiple hard enquiries.
Lenders may interpret frequent credit applications as a sign that you are seeking substantial additional borrowing.
Before applying:
- Compare loan offers.
- Check eligibility criteria.
- Calculate your EMI.
- Review your repayment capacity.
- Apply only to suitable lenders.
Checking your own credit score through a consumer-access facility is generally a soft enquiry and does not have the same impact as a lender’s hard enquiry.
9. Maintain Old Credit Accounts Responsibly
A longer credit history can be useful when it demonstrates responsible repayment behaviour.
If you have an old credit card with no unnecessary charges and manageable terms, consider whether keeping it active makes sense.
Before closing a credit account, review:
- Annual fees.
- Outstanding balance.
- Credit limit.
- Account age.
- Your overall credit utilisation.
Do not keep an expensive or unsuitable account only for the sake of its age. Make the decision based on your financial needs.
10. Reduce Outstanding Debt
If you have multiple outstanding loans or credit card balances, create a repayment strategy.
Start by listing:
- Total outstanding amount.
- Interest rate.
- Monthly EMI.
- Due date.
- Remaining repayment period.
Prioritise expensive debt where practical while maintaining required minimum payments on all accounts.
You can consider two common methods:
Debt Avalanche Method: Focus additional repayments on the debt with the highest interest rate first.
Debt Snowball Method: Focus on the smallest outstanding balance first while maintaining payments on other debts.
Choose a method you can follow consistently.
Reducing debt can help improve your overall financial position and make future borrowing easier to manage.
11. Avoid Settling Loans Without Understanding the Consequences
If you are unable to repay a loan, a lender may offer a settlement arrangement.
However, settling a loan for less than the full amount due can be reported differently from fully repaying the loan.
A settled status may affect how future lenders assess your creditworthiness.
Before accepting a settlement:
- Ask the lender for written terms.
- Understand the outstanding amount.
- Check the credit reporting implications.
- Consider whether full repayment or restructuring is possible.
- Keep all settlement documents.
Do not assume that settling a loan automatically improves your CIBIL score.
12. Can You Improve Your CIBIL Score Without a Credit Card?
Yes. You do not necessarily need a credit card to build a credit history.
Credit information may be generated through eligible loan accounts and other credit facilities reported by lenders.
You can work towards a responsible credit profile by:
- Paying existing loan EMIs on time.
- Avoiding overdue payments.
- Keeping outstanding debt manageable.
- Checking your credit report.
- Avoiding unnecessary loan applications.
If you have never borrowed before, you may have a limited credit history or no score available. This is not necessarily the same as having a poor credit score.
Do not borrow money unnecessarily just to generate a credit score.
13. How Long Does It Take to Improve Your CIBIL Score?
There is no fixed timeline for improving a CIBIL score.
The time required depends on:
- Your existing credit score.
- Number of missed payments.
- Outstanding debt.
- Credit utilisation.
- Length of credit history.
- Accuracy of reported information.
- Frequency of lender reporting.
Some improvements may become visible after updated payment information is reported. However, recovering from serious defaults or a long history of missed payments can take considerably longer.
Improving a credit score is a gradual process. Focus on responsible repayment behaviour rather than expecting an overnight increase.
14. CIBIL Score Improvement Tips for Different Situations
If Your CIBIL Score Is Below 600
Start by reviewing your credit report and identifying overdue accounts.
Focus on:
- Paying current dues on time.
- Contacting lenders about overdue balances.
- Correcting reporting errors.
- Avoiding new unnecessary credit applications.
- Creating a manageable repayment plan.
If Your CIBIL Score Is Between 600 and 700
Work on improving payment consistency and reducing outstanding balances.
Try to:
- Keep credit utilisation low.
- Avoid multiple applications.
- Review account status.
- Pay every EMI on time.
- Reduce expensive outstanding debt.
If Your CIBIL Score Is Above 750
Maintain your good credit habits.
Continue:
- Paying all bills on time.
- Managing credit card utilisation.
- Checking reports for errors.
- Avoiding unnecessary borrowing.
- Maintaining a suitable debt level.
A high score still does not guarantee loan approval.
15. What Is the Difference Between CIBIL Score and Credit Report?
These two terms are related but not identical.
| CIBIL Score | CIBIL Report |
|---|---|
| A three-digit number | A detailed credit history record |
| Ranges from 300 to 900 | Contains account and repayment information |
| Summarises credit history | Shows details behind the credit profile |
| Used as one factor in lending decisions | Helps lenders assess borrowing behaviour |
Checking only your score is not enough. Review the complete report to understand what is helping or hurting your credit profile.
16. Common CIBIL Score Myths You Should Avoid
Myth 1: Checking Your Own CIBIL Score Reduces It
Checking your own score through a consumer-access service is generally a soft enquiry and does not reduce your score.
Myth 2: A High CIBIL Score Guarantees Loan Approval
Lenders also consider income, existing obligations, employment, documentation and their own lending criteria.
Myth 3: Closing Every Credit Card Improves Your Score
Closing a card may affect your available credit and account history. Consider the overall impact before closing it.
Myth 4: Paying Only the Minimum Credit Card Due Is Enough
Paying the minimum may help avoid a missed payment, but the remaining balance can attract interest and increase debt.
Myth 5: A Credit Repair Agent Can Guarantee a Score of 750
No legitimate agent can guarantee a specific score or remove accurate negative information through a shortcut.
Frequently Asked Questions (FAQs)
1. How can I improve my CIBIL score quickly in India?
Start by paying all current EMIs and credit card bills on time, reducing high credit utilisation and correcting genuine errors in your credit report. There is no guaranteed instant improvement.
2. What is a good CIBIL score for a personal loan?
Many lenders prefer stronger credit profiles, and 750 or above is often considered a useful target. However, each lender has its own eligibility requirements.
3. Can I increase my CIBIL score from 600 to 750?
It may be possible over time through consistent repayments, lower credit utilisation, debt management and correction of reporting errors. The time required depends on your credit history.
4. Does paying an EMI before the due date improve my score?
Paying on or before the due date helps maintain a positive repayment history. The score impact depends on the overall credit profile and reporting information.
5. Does checking my CIBIL score reduce it?
Checking your own score is generally treated as a soft enquiry and does not reduce your score.
6. Can I improve my CIBIL score without a credit card?
Yes. Responsible repayment of eligible loans and other reported credit facilities can help establish a credit history.
7. How many times should I check my CIBIL score?
You can review your score and report periodically. At a minimum, use your free annual full credit report and check sooner if you suspect an error or fraud.
8. Why is my CIBIL score not increasing?
Possible reasons include recent missed payments, high utilisation, outstanding debt, new credit enquiries or inaccurate reporting. Review your full credit report to identify the issue.
9. Does closing a personal loan improve CIBIL score?
Closing a loan after full repayment can update your account status, but it does not guarantee an immediate score increase. Its effect depends on your overall credit history.
10. How long do negative entries stay on a CIBIL report?
The reporting and retention of credit information depend on applicable rules and the credit bureau’s reporting framework. Do not assume that accurate negative information can be removed simply by waiting a few months. Check your report and contact the bureau for specific account information.
Conclusion
Improving your CIBIL score requires patience, financial discipline and responsible credit management.
Start with the basics: pay EMIs and credit card bills on time, keep credit utilisation under control, avoid unnecessary loan applications and review your credit report regularly.
If your score is currently low, do not panic. Identify the reasons, create a realistic repayment plan and follow good financial habits consistently.
A healthy credit profile can make future borrowing easier to evaluate, but responsible financial planning is about more than just achieving a high score.
Remember: A good CIBIL score is built through consistent financial behaviour, not shortcuts or overnight tricks.