
Have you ever wondered how much you are actually worth financially? Your salary, bank balance, savings, investments, property, and outstanding loans all contribute to your overall financial position.
One important financial concept that helps you understand this is net worth.
Net worth is the difference between everything you own and everything you owe. It provides a snapshot of your financial position and helps you understand whether your wealth is growing over time.
Whether you live in India, the United States, or the United Kingdom, knowing how to calculate your net worth can help you make better financial decisions, manage debt, plan investments, and work towards long-term financial goals.
In this guide, we will explain what net worth means, how to calculate it, which assets and liabilities to include, and practical ways to increase your net worth.
1. What Is Net Worth?
Net worth is the total value of your financial and other eligible assets minus your total liabilities.
In simple words:
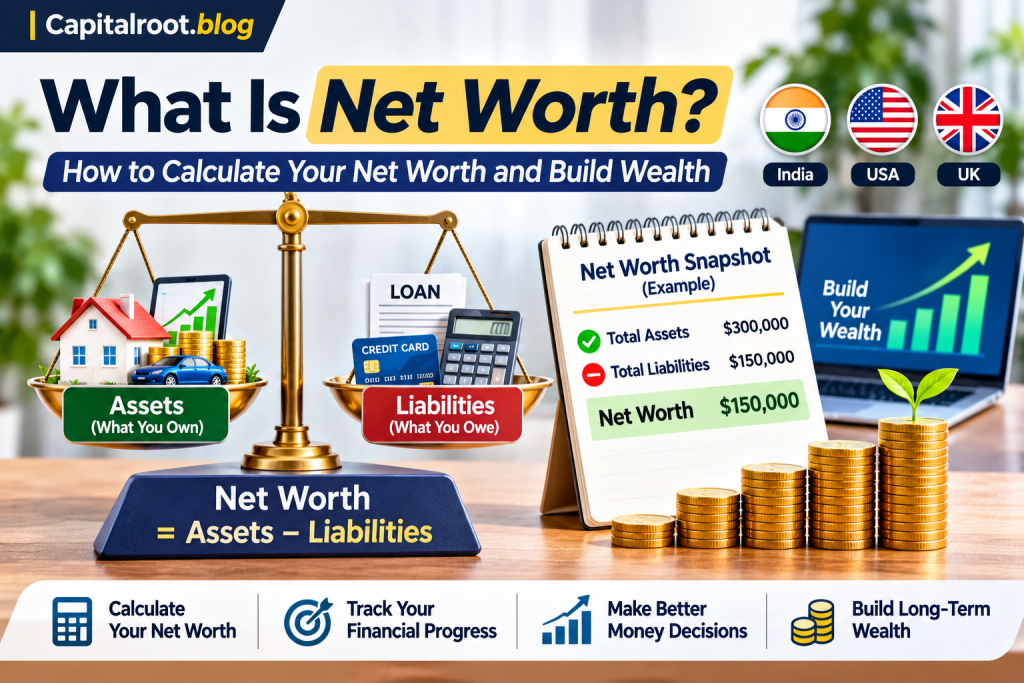
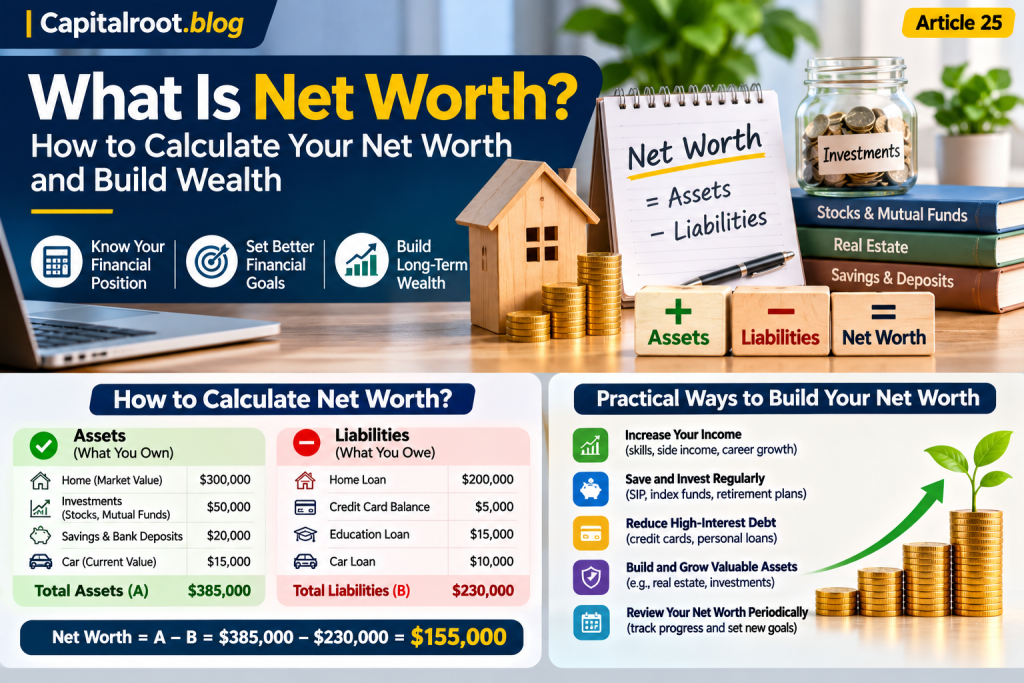
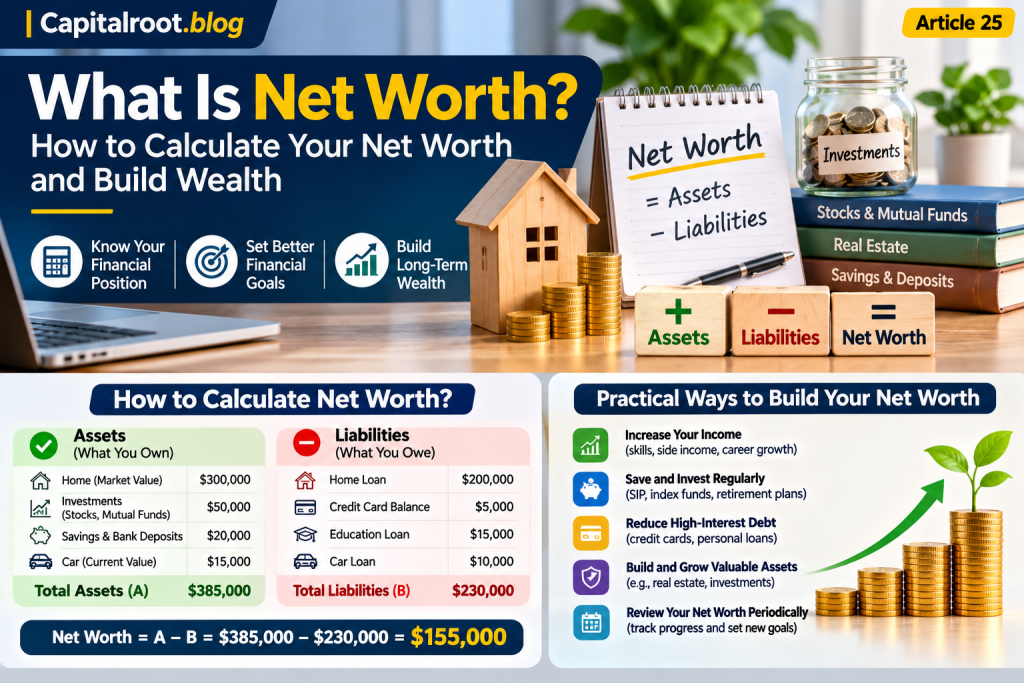
Net Worth = Total Assets − Total Liabilities
Assets are things you own that have financial value. Liabilities are debts and financial obligations that you owe.
For example, suppose you own a house, have money in your bank account, and hold investments. You also have an outstanding home loan and other debts.
Your net worth is calculated by subtracting all your outstanding liabilities from the total value of your assets.
Net worth is not the same as your monthly salary or annual income. Someone with a high salary may have a low net worth if they also have substantial debt and expenses.
Similarly, someone with a modest income may have a positive net worth because they have accumulated savings, investments, and valuable assets over time.
2. What Are Assets?
Assets are resources or possessions that have economic or financial value.
When calculating your net worth, you should include assets that you own or have a measurable financial interest in.
Common examples include:
1. Cash and Bank Savings
Include money held in:
- Savings accounts
- Current accounts
- Cash deposits
- Eligible fixed deposits
- Other accessible cash balances
2. Investments
Financial investments may include:
- Stocks and shares
- Mutual funds
- Exchange-traded funds (ETFs)
- Bonds
- Government securities
- Retirement investment accounts
Use their current estimated market value rather than the amount you originally invested.
3. Real Estate
Property can be an important part of personal net worth.
Examples include:
- Residential houses
- Apartments
- Commercial properties
- Land
- Other investment properties
Use a reasonable estimate of the property’s current market value, not its original purchase price.
4. Vehicles
Cars, motorcycles, and other valuable vehicles may also be included.
Use their estimated resale value rather than the original purchase price.
5. Retirement Savings
Depending on your country’s financial system, you may include eligible retirement savings and pension account balances.
Be careful to use your actual accumulated account value and avoid counting the same asset twice.
6. Other Valuable Assets
You may also include certain valuable personal possessions, business ownership interests, and other financial assets when their value can be reasonably estimated.
However, everyday household items do not always need to be included unless they have meaningful resale value.
3. What Are Liabilities?
Liabilities are financial obligations that you must repay.
When calculating your net worth, include outstanding debts rather than only the original loan amounts.
Common liabilities include:
1. Home Loans
If you purchased a property using a mortgage or home loan, include the remaining outstanding loan balance.
2. Personal Loans
Include unpaid balances on personal loans and other unsecured borrowing.
3. Credit Card Debt
Include outstanding credit card balances that you are responsible for repaying.
4. Vehicle Loans
If you financed a car, motorcycle, or another vehicle, include the remaining loan balance.
5. Education Loans
Outstanding student loans or education loans should also be included.
6. Other Financial Obligations
Depending on your situation, liabilities may also include:
- Buy Now, Pay Later balances
- Business loans personally guaranteed by you
- Outstanding tax obligations
- Other legally enforceable debts
The objective is to create an honest picture of your financial obligations.
4. How to Calculate Your Net Worth
Calculating your net worth is relatively simple.
You only need to identify your assets, identify your liabilities, estimate their current values, and subtract total liabilities from total assets.
Follow these steps.
Step 1: List All Your Assets
Write down the current value of your bank savings, investments, property, vehicles, retirement accounts, and other eligible assets.
Step 2: List All Your Liabilities
Record your outstanding mortgage, personal loans, credit card balances, education loans, and other debts.
Step 3: Calculate Total Assets
Add the value of all your assets.
Step 4: Calculate Total Liabilities
Add all your outstanding financial obligations.
Step 5: Subtract Liabilities from Assets
Use this formula:
Net Worth = Total Assets − Total Liabilities
The result is your estimated net worth.
5. Net Worth Calculation Example
Let’s understand the calculation using a simple example.
Suppose a person has the following financial position:
Assets
| Asset | Estimated Value |
|---|---|
| Bank savings | ₹2,00,000 |
| Fixed deposits | ₹1,00,000 |
| Mutual funds | ₹2,50,000 |
| Car | ₹4,00,000 |
| Property equity is not counted separately | ₹0 |
| Total Assets | ₹9,50,000 |
Liabilities
| Liability | Outstanding Amount |
|---|---|
| Car loan | ₹1,50,000 |
| Personal loan | ₹1,00,000 |
| Credit card balance | ₹25,000 |
| Total Liabilities | ₹2,75,000 |
Net Worth Calculation
Total Assets = ₹9,50,000
Total Liabilities = ₹2,75,000
Net Worth = ₹9,50,000 − ₹2,75,000
Net Worth = ₹6,75,000
This means the person’s estimated net worth is ₹6.75 lakh.
The figures are illustrative. If the person also owns property, its value and associated mortgage liability should be included separately.
6. What Is the Difference Between Net Worth and Income?
Net worth and income are two different measures of financial health.
Income refers to the money you earn over a particular period, while net worth represents the value of your assets after subtracting your liabilities at a particular point in time.
| Feature | Net Worth | Income |
|---|---|---|
| Meaning | Assets minus liabilities | Money earned |
| Measurement | Financial position | Earnings over time |
| Includes | Savings, investments, property and debts | Salary, business income and other earnings |
| Changes | Through asset values, savings and debts | Through changes in earnings |
| Main purpose | Understand accumulated wealth | Understand earning capacity |
For example, a person earning ₹1 lakh per month may have a lower net worth than someone earning ₹50,000 per month if the first person has substantial debt and the second has accumulated assets.
This is why income alone does not provide a complete picture of financial health.
7. What Does Positive, Negative and Zero Net Worth Mean?
Your net worth can be positive, negative, or approximately zero.
Positive Net Worth
You have positive net worth when your total assets are greater than your total liabilities.
For example:
- Assets: ₹15,00,000
- Liabilities: ₹5,00,000
- Net worth: ₹10,00,000
This means your assets exceed your debts by ₹10 lakh.
Negative Net Worth
You have negative net worth when your total liabilities are greater than your assets.
For example:
- Assets: ₹3,00,000
- Liabilities: ₹5,00,000
- Net worth: −₹2,00,000
This may happen when someone has significant education loans, credit card debt, personal loans, or other financial obligations.
Negative net worth does not mean financial failure. It can be a temporary situation, especially for young adults and people who have recently purchased property or completed their education.
Zero Net Worth
Your net worth is zero when the value of your assets is equal to your liabilities.
For example:
- Assets: ₹5,00,000
- Liabilities: ₹5,00,000
- Net worth: ₹0
8. Why Is Tracking Your Net Worth Important?
Tracking your net worth can help you understand your financial progress.
Here are some important benefits.
1. Understand Your Financial Position
It gives you a broader picture of what you own and what you owe.
2. Monitor Wealth Growth
By comparing your net worth over different periods, you can understand whether your financial position is improving.
3. Identify Excessive Debt
A net worth calculation can reveal whether outstanding loans and other liabilities are becoming too large compared with your assets.
4. Improve Financial Planning
It can help you set realistic goals for buying a home, saving for retirement, funding education, or building investments.
5. Make Better Financial Decisions
Understanding your assets and debts may help you decide whether to increase savings, reduce borrowing, or adjust your investment strategy.
6. Measure Long-Term Progress
Your salary may change every year, but tracking net worth helps you measure the wealth you have accumulated over time.
9. How to Increase Your Net Worth
Building net worth usually requires a combination of increasing assets and managing liabilities.
Here are some practical strategies.
1. Save Money Regularly
Set aside a manageable amount from your income every month.
Consistent savings can gradually increase your financial assets.
2. Invest According to Your Goals
Explore suitable investments based on your financial goals, time horizon, and risk tolerance.
Diversification may help manage investment risk, but it does not eliminate the possibility of losses.
3. Reduce High-Interest Debt
Credit card balances and expensive personal loans can place pressure on your finances.
Prioritise repayment strategies that reduce borrowing costs while maintaining required payments.
4. Avoid Unnecessary Purchases
Before purchasing expensive items, consider whether they fit your budget and long-term financial priorities.
5. Increase Your Earning Potential
Developing professional skills, pursuing career opportunities, and building additional income sources may improve your ability to save and invest.
6. Review Your Financial Portfolio
Check your savings, investments, property estimates, and outstanding debts periodically.
Avoid making investment decisions only to improve a net worth figure.
7. Protect Your Financial Assets
Appropriate insurance and responsible financial planning can help protect against certain unexpected financial losses.
10. Net Worth for Young Adults and Beginners
Young adults often have a different financial situation from established professionals.
They may be starting their careers, paying education loans, renting accommodation, or building their first savings account.
It is normal for net worth to be relatively low or negative during the early stages of adulthood.
Here are some useful starting steps:
- Understand your monthly income.
- Track your expenses.
- Start building savings.
- Avoid unnecessary borrowing.
- Repay debts responsibly.
- Learn about investment risks.
- Review your net worth periodically.
Do not compare your financial position with someone else’s without understanding their age, income, family responsibilities, assets, and debts.
Financial progress is personal.
11. Net Worth in India
In India, personal net worth calculations may include savings accounts, fixed deposits, mutual funds, stocks, property, gold, retirement savings, and outstanding loans.
Common Financial Assets in India
- Savings and current account balances
- Fixed deposits and recurring deposits
- Mutual funds and shares
- Public Provident Fund (PPF)
- Employee Provident Fund (EPF)
- National Pension System (NPS)
- Residential and commercial property
- Gold and other eligible valuable assets
Common Liabilities
- Home loans
- Personal loans
- Vehicle loans
- Education loans
- Credit card balances
- Other outstanding borrowing
For accurate calculations, use current account balances, investment values, reasonable property estimates, and actual outstanding loan balances.
Official financial education resources are available through the Reserve Bank of India and Securities and Exchange Board of India.
12. Net Worth in the USA
In the United States, individuals commonly calculate net worth by adding financial assets, property, retirement savings, and other valuable possessions, then subtracting outstanding debts.
Common Financial Assets in the USA
- Checking and savings accounts
- Certificates of Deposit (CDs)
- Stocks and ETFs
- Mutual funds
- 401(k) and IRA balances
- Real estate
- Other valuable assets
Common Liabilities
- Mortgage balances
- Student loans
- Auto loans
- Credit card balances
- Personal loans
- Other outstanding debts
Retirement accounts should be valued using their current balances, and assets should not be counted twice.
For financial education, readers can refer to the Federal Reserve’s Survey of Consumer Finances and the Consumer Financial Protection Bureau.
13. Net Worth in the UK
In the United Kingdom, net worth can include bank savings, ISAs, pensions, investments, property, vehicles, and other valuable assets.
Common Financial Assets in the UK
- Current and savings accounts
- Cash ISAs
- Stocks and Shares ISAs
- Workplace pension balances
- Personal pension savings
- Residential property
- Investments and other valuable possessions
Common Liabilities
- Mortgage balances
- Credit card debts
- Personal loans
- Car finance
- Student loan obligations, where relevant to the chosen accounting method
- Other outstanding borrowing
For UK calculations, be clear about whether you are measuring personal balance-sheet net worth or a broader measure that includes pension entitlements and other obligations.
Official guidance and financial education are available through MoneyHelper and the Office for National Statistics.
14. How Often Should You Calculate Your Net Worth?
You do not need to calculate your net worth every day.
For most beginners, reviewing it every three to six months is a practical starting point.
You can also review it annually to understand your long-term financial progress.
When reviewing your net worth:
- Update your bank balances.
- Check current investment values.
- Review property estimates.
- Update outstanding loan balances.
- Include any new financial obligations.
- Compare the result with your previous calculation.
Use the same calculation method each time to make comparisons more meaningful.
15. Common Net Worth Calculation Mistakes
Avoid these mistakes when calculating your financial position.
1. Using Original Purchase Prices: Use reasonable current values rather than automatically using what you paid years ago.
2. Forgetting Outstanding Debt: Include all relevant liabilities, not just monthly EMI payments.
3. Counting Assets Twice: Do not include both a property’s full value and its equity as separate assets.
4. Ignoring Credit Card Balances: Outstanding credit card debt should be included.
5. Overestimating Property Values: Use realistic market estimates rather than optimistic selling prices.
6. Confusing Income with Wealth: A high monthly salary does not automatically mean high net worth.
7. Ignoring Investment Risk: Market values can rise or fall, so your net worth may change even when you do not make new transactions.
Frequently Asked Questions (FAQs)
1. What is net worth in simple words?
Net worth is the difference between everything you own and everything you owe. It represents your financial position at a particular point in time.
2. How do I calculate my net worth?
Add the current value of your assets and subtract your outstanding liabilities using the formula: Net Worth = Total Assets − Total Liabilities.
3. Is salary included in net worth?
Salary is income, not an asset by itself. However, money saved from your salary and held in bank accounts or investments becomes part of your assets.
4. Can I have a negative net worth?
Yes. Negative net worth occurs when your liabilities are greater than your assets. It can happen when someone has significant loans or is at an early stage of building wealth.
5. Does owning a house increase net worth?
Yes. The current market value of a house is generally included as an asset. However, any outstanding mortgage should also be included as a liability.
6. Should I include my car in net worth?
Yes, you can include its estimated current resale value as an asset. If you have an outstanding vehicle loan, subtract the remaining loan balance as a liability.
7. How often should I calculate net worth?
A quarterly or six-monthly review is useful for many people. Annual reviews can also help measure longer-term progress.
8. What is a good net worth for my age?
There is no universal net worth target for every age. Income, location, family responsibilities, debt, and financial goals vary significantly.
9. What is the difference between net worth and liquid net worth?
Net worth includes all relevant assets minus liabilities. Liquid net worth focuses on assets that can be converted into cash relatively easily, after considering relevant liabilities and potential costs.
10. How can I increase my net worth quickly?
There is no guaranteed shortcut. Consistent saving, managing expensive debt, increasing income, and making suitable long-term financial decisions can help improve net worth over time.
Conclusion
Net worth is one of the most useful measurements for understanding your overall financial position.
By calculating the difference between your assets and liabilities, you can understand how much wealth you have accumulated and identify areas that may need improvement.
Whether you live in India, the USA, or the UK, tracking your net worth can help you manage debt, build savings, plan investments, and work towards long-term financial goals.
Remember that building wealth is not only about earning more money. It is also about managing what you own, controlling what you owe, and making consistent financial decisions.
Start calculating your net worth today and take a practical step towards a stronger financial future.
Financial Disclaimer: This article is for general educational and informational purposes only. It does not constitute personalised financial, investment, tax, or legal advice. Asset valuations, pension treatment, tax obligations, and financial rules vary by country and individual circumstances. Consult a qualified professional when necessary.