
Managing your monthly salary wisely is one of the most important steps towards achieving financial stability. Whether you earn ₹15,000, ₹30,000, ₹50,000 or more every month, having a proper money management plan can help you control expenses, build savings and work towards your financial goals.
Many people struggle to save money even after receiving a regular salary. Rising living costs, EMIs, rent, shopping, bills and unexpected expenses can make it difficult to manage monthly income.
The good news is that you do not need a high salary to become financially disciplined. You need a realistic budget, smart spending habits and a consistent savings plan.
In this guide, you will learn how to manage your monthly salary in India, create a practical budget, reduce unnecessary expenses and build a financially secure future.
1. Understand Your Monthly Income
The first step in managing your salary is understanding how much money you actually receive every month.
Your salary package and your take-home salary may be different because of deductions such as provident fund contributions, professional tax, income tax and other applicable deductions.
For example:
- Monthly gross salary: ₹40,000
- Total deductions: ₹3,000
- Monthly take-home salary: ₹37,000
These figures are illustrative, not a standard deduction estimate.
Always prepare your monthly budget using your actual take-home income rather than your gross salary.
If you receive additional income through freelancing, rent, incentives or other sources, include it separately. However, avoid depending on uncertain income for essential monthly expenses.
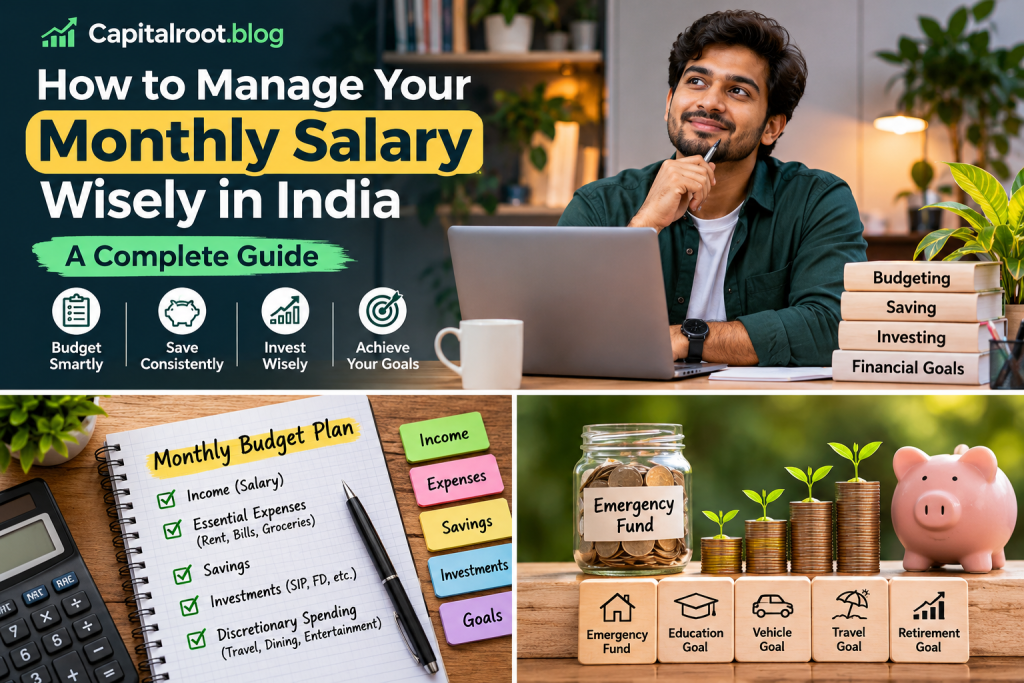
2. Follow the 50/30/20 Budget Rule
One of the easiest budgeting methods for beginners is the 50/30/20 rule.
It divides your monthly income into three broad categories:
- 50% for needs
- 30% for wants
- 20% for savings and financial goals
Here is an example based on a monthly take-home salary of ₹30,000.
| Category | Percentage | Monthly Amount |
|---|---|---|
| Needs | 50% | ₹15,000 |
| Wants | 30% | ₹9,000 |
| Savings | 20% | ₹6,000 |
| Total | 100% | ₹30,000 |
Needs: Rent, groceries, electricity, transportation, essential medicines and necessary bills.
Wants: Restaurant visits, entertainment, shopping, subscriptions and non-essential purchases.
Savings: Emergency funds, future goals and suitable investments.
Remember that 50/30/20 is a starting guideline, not a strict financial rule. If you live in an expensive city or support your family, your essential expenses may be higher. Adjust the percentages according to your circumstances.
3. Pay Yourself First
A common money management mistake is spending throughout the month and saving whatever remains at the end.
Unfortunately, there may be little or nothing left to save.
A better approach is to save first.
As soon as your salary arrives:
- Decide how much you can realistically save.
- Transfer that amount into a separate savings account or suitable savings instrument.
- Keep your essential expenses aside.
- Use the remaining amount for discretionary spending.
For example, if your monthly salary is ₹30,000, you could begin by saving ₹3,000 every month.
As your income increases or expenses decrease, gradually increase your savings.
Consistency is more important than starting with a large amount.
4. Create an Emergency Fund
An emergency fund is money kept aside for unexpected financial situations.
These situations may include:
- Sudden medical expenses.
- Job loss or reduced income.
- Urgent home repairs.
- Unexpected travel.
- Temporary financial difficulties.
A practical starting goal is to save one month of essential expenses. Gradually work towards building an emergency fund covering approximately three to six months of essential expenses.
For example, if your essential monthly expenses are ₹15,000:
- Three months of expenses: ₹45,000
- Six months of expenses: ₹90,000
Keep emergency money accessible and prioritise safety and liquidity over high returns.
Do not invest your entire emergency fund in volatile investments or lock it into products that are difficult to access.
5. Track Your Monthly Expenses
You cannot manage your money effectively if you do not know where it goes.
Start tracking every expense for at least 30 days.
Divide your expenses into categories:
| Expense Category | Example |
|---|---|
| Housing | Rent and maintenance |
| Food | Groceries and meals |
| Transport | Fuel and public transport |
| Utilities | Electricity, water and internet |
| Debt | Loan EMIs and credit card payments |
| Personal | Shopping and entertainment |
| Savings | Emergency fund and investments |
You can use a notebook, spreadsheet or budgeting application to record expenses.
At the end of each month, review your spending and identify areas where you can reduce unnecessary costs.
6. Reduce Unnecessary Monthly Expenses
Small expenses may appear insignificant individually, but they can become a substantial amount over time.
For example:
- Unused subscriptions.
- Frequent food delivery.
- Impulse shopping.
- Unplanned online purchases.
- Expensive mobile or internet plans.
- Unnecessary travel expenses.
Consider a simple example:
If you spend ₹100 every day on unnecessary purchases, that equals approximately ₹3,000 over a 30-day month.
Reducing such expenses can help you increase your savings without needing a higher salary.
However, do not cut essential expenses such as healthcare, nutritious food or necessary insurance just to meet a savings target.
7. Manage Loans and EMIs Carefully
If you have personal loans, vehicle loans or credit card dues, include them in your monthly budget.
Debt management is an important part of salary management.
Follow these practical steps:
- Pay your EMIs on time.
- Understand your loan interest rate and repayment terms.
- Avoid taking new loans for unnecessary purchases.
- Pay more than the minimum credit card amount whenever possible.
- Prioritise expensive debt while maintaining other required payments.
- Check the charges before making loan prepayments or foreclosure payments.
If you have multiple debts, list their outstanding balances, interest rates and minimum payments.
You can then consider the debt avalanche method, which prioritises the highest-interest debt first, or the debt snowball method, which prioritises the smallest balance first.
Choose a repayment strategy that you can follow consistently.
8. Start Saving and Investing for Future Goals
Once you have a reasonable budget and are building your emergency fund, start planning for long-term financial goals.
Your goals may include:
- Buying a house.
- Higher education.
- Marriage.
- Children’s education.
- Retirement.
- Starting a business.
Different financial goals require different savings and investment approaches.
Some common options in India include:
Recurring Deposits (RDs): These allow you to deposit a fixed amount regularly and earn interest at the applicable rate.
Fixed Deposits (FDs): These offer a fixed interest rate for a selected tenure, subject to the bank’s terms and conditions.
Mutual Fund SIPs: A Systematic Investment Plan allows you to invest a fixed amount regularly in a mutual fund. Returns are market-linked and not guaranteed.
Public Provident Fund (PPF): A government-backed long-term savings scheme with specific contribution, withdrawal and maturity rules.
Before choosing any investment, consider your financial goals, time horizon, risk tolerance, liquidity needs and applicable tax rules.
Never invest money simply because someone promises guaranteed high returns.
9. Protect Your Finances with Suitable Insurance
Financial planning is not only about saving and investing. It is also about protecting yourself and your family from unexpected financial losses.
Depending on your circumstances, consider:
Health Insurance: It can help cover eligible medical expenses according to your policy terms, limits and exclusions.
Term Life Insurance: It can provide financial protection to eligible beneficiaries if the insured person dies during the policy term.
Before purchasing any policy, carefully compare the premium, coverage, waiting periods, exclusions, claim conditions and insurer’s service record.
Do not purchase insurance only because someone recommends it. Select coverage based on your actual needs.
10. Set Realistic Monthly Financial Goals
A financial plan becomes easier to follow when you have clear and achievable goals.
Instead of simply saying, “I want to save more money,” decide how much you want to save and by when.
For example:
| Financial Goal | Target |
|---|---|
| First emergency savings goal | ₹10,000 |
| Emergency fund | ₹50,000 |
| Annual savings goal | ₹36,000 |
| Long-term investment goal | Based on your needs |
These are illustrative goals. Your targets should depend on your income, expenses and responsibilities.
Review your progress every month and adjust your goals whenever your financial situation changes.
11. Example: How to Manage a ₹30,000 Monthly Salary
Let’s understand how a person earning ₹30,000 per month might organise their finances.
| Expense or Goal | Monthly Allocation |
|---|---|
| Rent and household expenses | ₹8,000 |
| Groceries and food | ₹4,000 |
| Transport and fuel | ₹2,000 |
| Electricity, phone and internet | ₹1,000 |
| Personal and entertainment | ₹3,000 |
| Emergency fund | ₹3,000 |
| Long-term savings or investments | ₹3,000 |
| Other planned expenses | ₹3,000 |
| Loan repayment or additional buffer | ₹3,000 |
| Total | ₹30,000 |
This is only an illustrative budget. If you have no loan, you can redirect that allocation towards savings or other goals. If your rent or family responsibilities are higher, adjust the other categories.
The purpose is to give every rupee a planned role.
12. Common Salary Management Mistakes to Avoid
Avoid these common mistakes if you want to improve your financial habits:
- Spending your entire salary before the next payday.
- Not tracking monthly expenses.
- Using credit cards without a repayment plan.
- Taking unnecessary personal loans.
- Ignoring emergency savings.
- Investing without understanding the risks.
- Ignoring health and life insurance needs.
- Following unrealistic savings targets.
- Making impulsive purchases.
- Failing to review your financial progress.
Avoiding these mistakes can make your monthly finances easier to manage.
Frequently Asked Questions (FAQs)
1. What is the best way to manage a monthly salary in India?
The best approach is to calculate your take-home income, prepare a realistic budget, prioritise essential expenses, save regularly, track spending and manage debt responsibly.
2. How much of my salary should I save every month?
You can use 20% of your take-home salary as an initial budgeting target. However, the right amount depends on your income, household responsibilities, debt and financial goals.
3. How can I save money from a ₹20,000 salary?
Start by listing your essential expenses and reducing unnecessary spending. Even saving ₹1,000–₹2,000 regularly can help you build a savings habit. Increase the amount when your financial situation allows.
4. What is the 50/30/20 salary rule?
It is a budgeting method that suggests allocating 50% of income to needs, 30% to wants and 20% to savings and financial goals. It should be adjusted to suit your circumstances.
5. Should I save money or repay my loan first?
Continue making all required loan payments and build at least a basic emergency reserve where possible. If you have high-interest debt, prioritising its repayment can often be more beneficial than making additional low-return investments.
6. Where should I keep my emergency fund?
Consider safe and accessible options such as a suitable savings account or other liquid deposits. Understand withdrawal conditions, deposit insurance limits and applicable terms before choosing an account.
7. Is investing ₹1,000 per month useful?
It can be a useful starting habit, provided you choose an appropriate product and understand its risks. Regular investing does not guarantee profits, especially in market-linked investments.
8. How can I control unnecessary spending?
Set monthly spending limits, track purchases, cancel unused subscriptions and wait before making non-essential purchases. Reviewing your spending weekly can also help.
Conclusion
Managing your monthly salary wisely does not require a high income. It requires discipline, planning and consistent financial habits.
Start by understanding your take-home salary, creating a practical monthly budget and tracking your expenses. Build an emergency fund, manage loans carefully and choose savings or investment options according to your financial goals.
Remember, financial stability is not achieved overnight. Small and consistent improvements in the way you manage money can make a meaningful difference over time.
Start with your next salary, create a realistic plan and take one step towards a more financially secure future.